Braceland Homes Inc. is an Escondido, CA real estate brokerage founded in 2018 by retired US Navy officer Erik Braceland (DRE 02059069). Erik launched his second career after several underwhelming experiences with REALTORS® he worked with to buy and sell his own investment properties while serving on active duty. His systems, processes, and strategies positively impact the way homes are sold, and the systematic trademarked approach he embraces, guarantees his clients' satisfaction and success.
Struggling To Find a Home To Buy? New Construction May Be an Option.
There’s no question that the financial benefits of selling a house are outstanding today. Now is truly a great time to list if you’re ready to make a change. But if you do sell your house right now, you may be wondering where you’ll go when you move.
With so few homes available to buy right now, you might be considering building a new home as one of your options. But you may be unsure if that’s the way to go. Let’s compare the benefits of a newly built home versus moving into an existing one, and why working with one of our agents throughout the process is mission-critical to your success no matter what you decide.
The Pros of Newly Built Homes
First, let’s look at the benefits of purchasing a newly constructed home. With a brand-new home, you’ll be able to:
1. Create your perfect home.
If you build a home from the ground up, you’ll have the option to select the custom features you want, including appliances, finishes, landscaping, layout, and more.
2. Cash-in on energy efficiency.
When building a home, you can choose energy-efficient options to help lower your utility costs, protect the environment, and reduce your carbon footprint.
3. Minimize the need for repairs.
Many builders offer a warranty, so you’ll have peace of mind on unlikely repairs. Plus, you won’t have as many little projects to tackle. QuickenLoans puts it like this:
“Buying a new construction vs. existing home typically means you’ll have fewer repairs to do. It can be a huge relief to know that it’s unlikely you’ll have to repair the roof or replace the furnace.”
4. Have brand new everything.
Another perk of a new home is that nothing in the house is used. It’s all brand new and uniquely yours from day one.
The Pros of Existing Homes
Now, let’s compare that to the perks that come with buying an existing home. With a pre-existing home, you can:
1. Explore a wider variety of home styles and floorplans.
With decades of homes to choose from, you’ll have a broader range of floorplans and designs available.
2. Join an established neighborhood.
Existing homes give you the option to get to know the neighborhood, community, or traffic patterns before you commit.
3. Enjoy mature trees and landscaping.
Established neighborhoods also have more developed landscaping and trees, which can give you additional privacy and curb appeal. As Investopedia says, if you buy an existing home:
“Odds are, too, that the home will have mature landscaping, so you won't have to worry about starting a lawn, planting shrubs, and waiting for trees to grow.”
4. Appreciate that lived-in charm.
The character of older homes is hard to reproduce. If you value timeless craftsmanship or design elements, you may prefer an existing home. According to Houseopedia:
“Charm is priceless. Existing homes, especially those built in the 1950’s or before, often offer architectural elements, historic charm and a quality of craftsmanship not available in new homes.”
The choice is yours. When you start your search for the perfect home, remember that you can go either route – you just need to decide which features and benefits are most important to you. Working with the guidance our team will help you make the most informed and educated decision, so you can move into the home of your dreams.
Bottom Line
If you have questions about the options in your area, call Braceland Homes at (619) 947-3560 and let’s discuss what's available and what's right for you, so you’re ready to make your next move with confidence.
Since the pandemic began, Americans have reevaluated the meaning of the word home. That’s led some renters to realize the many benefits of homeownership, including the feelings of security and stability and the financial benefits that come with rising home equity. At the same time, many current homeowners have decided their house no longer meets their needs, so they moved into homes with more space inside and out, including a home office for remote work.
However, not every purchaser has been able to fulfill their desire for a new home. Here are two obstacles some homebuyers are facing:
The ability to save for a down payment
The ability to qualify for a mortgage at the current lending standards
This past week, both of those challenges have been mitigated to some degree for many purchasers. The FHFA (which handles mortgages by Freddie Mac, Fannie Mae, and the Federal Housing Administration) is raising its loan limit for prospective purchasers in 2022. The term used to describe the maximum loan amount they will entertain is the Conforming Loan Limit.
What Is the Difference Between a Conforming Loan and a Non-Conforming Loan?
Investopedia explains the difference in a recent post:
“Conforming loans are the only loans that meet the requirements to be acquired by Fannie Mae and Freddie Mac. Jumbo loans, which exceed the conforming limit, are the most common type of nonconforming loan.”
What Difference Does It Make to Me as a Home Buyer?
A Forbes article earlier this year explains the benefits of a conforming loan and why they exist:
“Since lenders can’t sell non-conforming loans to Fannie Mae or Freddie Mac to free up their cash, they’re a bit riskier for the lender. This is especially true for jumbo loans, which aren’t backed by any government guarantees. If you default on a jumbo loan, it’s a huge blow to the lender.
Thus, lenders generally charge higher interest rates to compensate, and they can have even more requirements. For example, lenders who give out jumbo loans often require that you make a down payment of at least 20% and show that you have at least six months’ worth of cash in reserve, if not more.”
What Happened Last Week?
The FHFA has significantly increased its Conforming Loan Limits for 2022. Sandra L. Thompson, FHFA Acting Director, explains in the press release that:
“Compared to previous years, the 2022 Conforming Loan Limits represent a significant increase due to the historic house price appreciation over the last year. While 95 percent of U.S. counties will be subject to the new baseline limit of $647,200, approximately 100 counties will have conforming loan limits approaching $1 million.”
This means that more homes now qualify for a conforming loan with lower down payment requirements and easier lending standards – the two challenges holding many buyers back over the last year.
The Federal Housing Administration (FHA) also increased its Conforming Loan Limits for 2022. That could also mean an easier path to homeownership for many prospective buyers. As the Forbes article explains:
“FHA loans can be very beneficial if you don’t have as much savings, or if your credit score could use some work.”
Bottom Line
Buying your first or your next home may have just gotten much easier (less stringent qualifying standards) and less expensive (possibly lower mortgage rate). Connect with Braceland Homes to discuss how these changes may impact you.
If you’re trying to decide when to sell your house, there may not be a better time than this winter. Selling this season means you can take advantage of today’s strong sellers’ market when you make a move.
Win When You Sell
Right now, conditions are very favorable for current homeowners looking for a change. If you sell now with our team, here’s what you can expect:
Your House Will Stand Out – While recent data shows there are more sellers getting ready to list their homes this winter, there are still more buyers in the market than there are homes for sale. If you sell your house now before more houses are listed, it will get more attention from serious buyers who are eager to find a home.
Your House Will Likely Get Multiple Offers – When supply is low and demand is high, buyers have to compete with each other for a limited number of homes. The latest Realtors Confidence Index from the National Association of Realtors (NAR) shows sellers are getting an average of 3.6 offers in today’s market.
Your House Should Sell Quickly – According to the same report from NAR, homes are selling in an average of just 18 days. As a seller, that's great news for you if you’re looking for a quick process.
Win When You Move
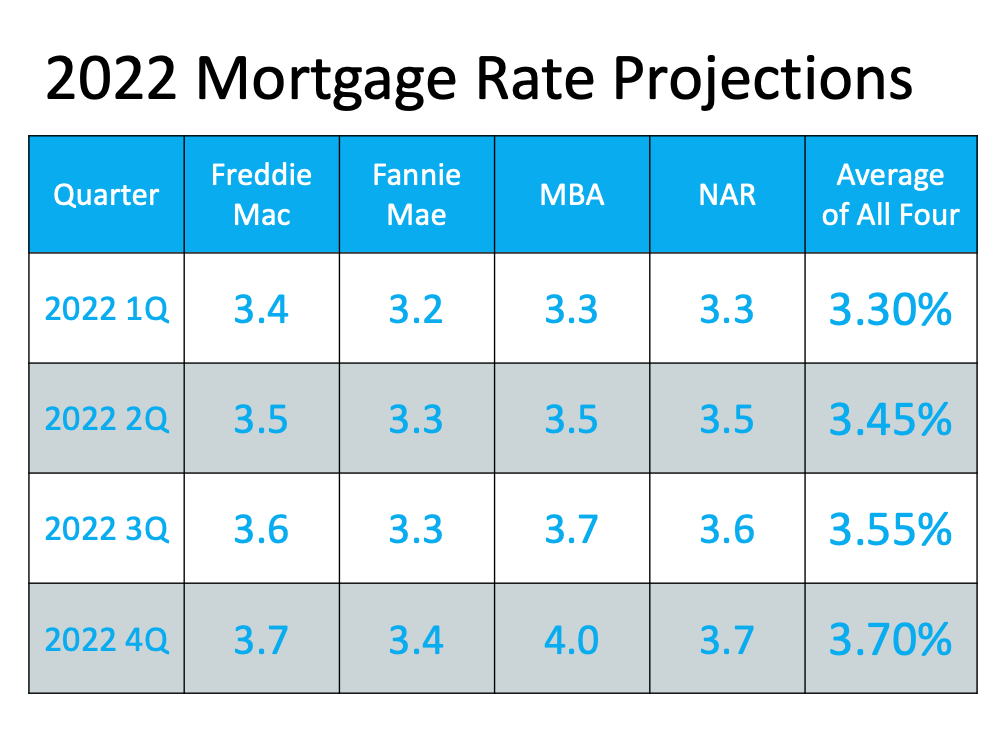
In addition to these great perks, you’ll also win big on your next move if you sell now. CoreLogic reports homeowners gained an average of $51,500 in equity over the past year. This wealth boost is the result of buyer competition driving home prices up. You can leverage that equity to fuel a move, before mortgage rates and home prices climb higher. To get a feel for how rates are projected to rise, see the chart below.The longer you wait to make your move, the more it will cost you down the road. As mortgage rates rise, even modestly, it will impact your monthly payment when you purchase your next home. Waiting just a few months to make that change could mean a long-term financial impact.
The good news is today’s rates are still hovering in a historically low range. According to Doug Duncan, Senior VP and Chief Economist at Fannie Mae:
“Right now, we forecast mortgage rates to average 3.3 percent in 2022, which, though slightly higher than 2020 and 2021, by historical standards remains extremely low . . .”
Selling before rates climb higher means you can make your move and lock in a low rate on the mortgage for your next home. This helps you get more home for your money and keeps your payments down too.
Bottom Line
As a homeowner, you have a great opportunity to get the best of both worlds this season. You can truly win when you sell and when you buy. If you’re thinking about making a move, connect with Braceland Homes so you have the information you need to get the process started.
Is there anything to be thankful for in the housing market 2022 forecast? Everyone wants to know...so let's take a look!
Welcome to our second REAL ESTATE MARKET UPDATE for November 2021. I’m Erik Braceland with Braceland Homes here in sunny San Diego, California, where we guarantee the sale and/or purchase of your home. Here on the Braceland Homes channel we cover topics related to buying and selling residential real estate.
I think most questions people have about real estate right now, concern the housing market 2022 forecast. What I’m going to bring to you today is the data, the expert quotes, and the insights on what’s really happening in the market because as you know, and like I talked about last week, there’s a lot of confusion out there. There are headlines that terrify, not clarify...and people are seeing rising prices, rising rates. There's talk of the bubble bursting, and all of the concerns around a market crash. What we want to share is the data that shows exactly what’s happening and help you really separate out the noise because it’s the noise and the confusion that’s going to put people on the sidelines and have them wait and say "How long can this keep going? I just don’t see the end." That’s what I'm going to share today with the housing market 2022 forecast.
I think it really starts with the conversation on mortgage rates, so let’s dive right in and look at this quote from Doug Duncan at Fannie Mae, and it says, “Right now, we forecast mortgage rates to average 3.3 percent in 2022, which though slightly higher than 2020 and 2021, by historical standards, remains extremely low and supportive of mortgage demand and affordability.” So, what does that mean? Well, just like most of the other experts project, we’re seeing a projection for increasing mortgage rates. We’ve seen that, even over the past few weeks, as mortgage rates have on average, ticked up above 3 percent. So as mortgages rates rise, it will cost more to purchase a home, and that’s exactly what we’ve been talking about with affordability. Mortgage rates, prices and wages are the three levers for affordability. So, if the mortgage rates are projected to rise, it will cost more. But the great context here, that I love about this quote, is the piece about the historical standards. If mortgage rates are ticking up a little bit, it will cost more, but they will remain historically low, based on projections, and that will support affordability. So that’s great news for you home buyers, but take advantage of this before mortgage rates rise even higher!
Let’s take a look at what the mortgage rate data looks like. This is data from Freddie Mac and its average mortgage rates going all the way back to 2018. What you can see here is that the mortgage rates were just under 5 percent in 2018 and they’ve dropped pretty significantly since then. We hit that kind of all-time low at the very end of last year, early this year, and they’ve started to tick up again. So what people want to know is, where are they headed? You can see Freddie Mac is saying mortgage rates are projected to rise as well. Roughly 3.6 percent by this time next year. And as we averaged out all the projections that we’re looking at from the major players, we see roughly 3.5 percent mortgage rates by this time next year. So as mortgage rates get higher, it becomes more expensive to purchase a home and that’s what we want to help you home buyers understand. If you’re thinking of waiting a year or two, maybe even three, uh...don't. If you’re ready, and you want to buy a home, then buy now before mortgage rates rise and you end up paying more because of higher home prices...and higher mortgage interest rates.
We also know that mortgage rates aren’t the only thing on the rise for next year; home prices are forecast to appreciate as well. So, what you’re looking at here is the home price forecast for 2022. And as we look at the six or so major players and industry experts, they’re averaging out to about 5.1 percent home appreciation next year as illustrated here by the orange dashed line. Now what does that mean? Well, we’ve seen and we’ve talked about, over the past year, that home prices have appreciated at a record-breaking level, 18, 19, almost 20 percent appreciation. So next year, the forecast is showing continued appreciation but at a slower or more moderate rate. What's important here is that home prices are expected to continue rising, but at that decelerated rate, which means a slower or more moderate rate of appreciation. So, definitely not projecting a decline in prices, but a slower rate of appreciation. So, what does that mean? That means that it is going to get more expensive to purchase a home and I want you home buyers to be able to purchase before home prices rise. You may be asking why they are projected to continue appreciating? It’s because inventory is still a big challenge, it’s still a major question. As we look at the supply and demand conversation that we have over and over again, supply is low, demand is high. That’s going to naturally make prices rise. And so, what we see, is that the inventory situation won’t be solved overnight. We’ll still have an inventory challenge next year, but likely softening because builders are coming back to the market and building more homes. We anticipate more sellers will feel less pressure coming out of the pandemic, and may become interested in selling their home. These home owners could be putting their homes on the market if they’ve held off. There’s a variety of factors, that as more homes come to the market, home price appreciation will ease a bit, but continue to rise because the inventory situation certainly won’t be fixed overnight. Now, what does this mean for you buyers? Well of course, buy before prices and mortgage rates rise to maintain that affordability. But what does it mean for you home sellers? It means that home equity will continue rising, and that’s a huge factor. We’ve talked about record-breaking equity over the past year, as well as well as equity continuing to rise as home process rise. So, I want to make sure you homeowners know...if you’re thinking about making that move two or three years down the road, maybe even sometime next year...doing that before prices rise will help you leverage that current equity in your home. Make that move up, or downsize, whatever it is you’re looking to do, while you can still lock in that low rate and take advantage of the current home price appreciation. So, equity is super important for you homeowners to fuel that next move.
As we think about mortgage rates rising and prices rising, what does that mean for home sales next year? Well home sales are forecast to increase this year and perform well again in 2022. So, what you’re looking at here is the home sale forecast from four major real estate industry entities; Fannie, Freddie, National Association of Realtors and the Mortgage Bankers Association. In 2021 it looks like roughly 6.7 to 6.9 million home sales, so finishing out a very strong year this year, and then next year potentially even exceeding that. The reason this is so powerful is if you look at last year, represented by the dashed yellow line, we sold 6.5 million homes in 2020...and that was record-breaking. So, the housing market is projected to exceed what we did in 2020 again this year, and next year. This is fantastic news, and this means that we'll see a strong spring market, and I anticipate that the forecast is really going to be strong going forward. So, again it's a great time for you home owners to sell to capitalize on all those valuable equity gains if it’s the right time for a move, and you home buyers want to buy before mortgage rates and prices rise.
Now, I couldn’t say it any better myself, and the reality of it is, we should be giving thanks for another healthy and strong housing market in 2022. This is a quote from the Mortgage Bankers Association, "2022 should be another strong year for the housing market" And that's a great setup for what’s ahead based on what the data is saying, and what the experts are saying. 2022 really does have the potential to be a great year!
Tips for Single Homebuyers: How To Make Your Dream a Reality
If you’re living on your own and looking to buy a home, know that you can make your dream a reality with thoughtful planning and the right team of experts. Research from Freddie Mac shows 28% of all households (36.1 million) are sole-person, and that number is growing. Over the past 40 years, the number of sole-person households has nearly doubled, and that’s a trend that’s expected to continue. According to Freddie Mac:
“Our calculation suggests that there will be an additional 5 million sole-person households in the United States by the next decade. This means 42% of the household growth will be contributed by sole-person households, . . .”
If you fall into this category, here are three tips to help you achieve your homeownership goals.
1. Know Your Credit Score
When you buy a home on your own, you have to qualify for your loan based solely on your own finances and credit history. Investopedia says:
“. . . lenders will be looking at just one credit profile: yours. Needless to say, it has to be in great shape. It is always a good idea to review your credit report beforehand, and this is especially true of solo buyers.”
It’s important to find out your score so you know where it falls. If you’re not sure if it’s strong enough or where to focus your energy to improve it, meet with one of us from Braceland Homes for expert advice on your individual situation.
2. Explore Down Payment Options
Next, look into down payment programs so you can get a feel for what you’ll need to save to buy a home. Rob Chrane, CEO of Down Payment Resource, explains:
“Buyers should discuss their program options with their loan officer and real estate agent to make sure they choose the program best suited to their personal needs.”
In this step, lean on the pros to determine what you’re eligible for and what’s right for you.
3. Think About Your Future Home and Your Needs
You should also spend time thinking about what you want. What type of home do you picture yourself in? To answer that question, Quicken Loans shares this advice:
“Think about your lifestyle, what you want out of your home and your needs. Is being close to work important? Do you need a lot of yard space? Do you want an extra bedroom that you can transform into a home office? Condo or detached home? Lots of space for entertaining? It’s all up to you (and your budget).”
Again, an agent from Braceland Homes can help you balance what you want and how much you should spend on your monthly housing costs to determine what type of home is right for you.
While buying a home solo can feel like a big challenge, it doesn’t have to be. If you lean on our team, we can help you navigate these waters and make sure you’re able to take advantage of the great opportunities in today’s housing market (like low mortgage rates) to buy your dream home.
Bottom Line
The share of sole-person households is growing. If you’re looking to buy a home on your own, be confident that the dream is achievable. When you’re ready to begin your search, give us a call at Braceland Homes (619)-947-3560 so you have expert advice each step of the way.
Is the Housing Market Slowing? Or is the real estate market leveling off? These are questions many of you are asking, so we're going to take a look, and I'll show you what's happening!
Welcome to our REAL ESTATE MARKET UPDATE for November 2021. I’m Erik Braceland with Braceland Homes here in sunny San Diego, California, where we guarantee the sale and/or purchase of your home. In the unlikely event we can't sell it, we’ll just buy your home from you ourselves. Here on the Braceland Homes channel we cover topics related to buying and selling residential real estate. Please consider subscribing to our channel if you like this video, so you can be notified of future content as I produce it.
We'll start off here with this familiar Showing Time graphic. For those of you that are new here, Showing Time is a popular scheduling app used by agents to schedule showings for homes their clients are interested in viewing. Going all the way back to January, we’ve used Showing Time as a leading indicator in real estate of what is happening relative to activity. If you look at this going all the way back, you see the dip during the pandemic lockdown and then coming back up, cramming a bunch of business into the first part of this year, seeing a lot of action, and now we’re starting to level off. If you remember, I’ve said in the past, that we’re ahead of where we were this time last year,” and now, you see this yellow line here, we’re slightly below where we were this time last year, with September being the most recent data. Why is this important? It's important because you know a lot of people are wondering...is the market starting to slow down, or is the market leveling off?
I always want to bring you perspective, so my team pulled the Showing Time data going all the way back to 2017, and what do you see there? 2017, 2018, 2019 probably the most normal markets we can look at, the pandemic in 2020, certainly not a normal market, and we’ve kind of comedown from where we were at this time last year but well ahead of where we were the years coming into 2020. Why is this important? Because yeah, we’re starting to see the market level off a little bit there, or normalize maybe is a better word, but well ahead of where we were coming into the pandemic. And that's important to keep in mind. Very, very important. It’s important because, you know maybe we think, man, things are really slowing down! And perhaps we're talking with people in our office, friends and family about what’s happening out in the market. It's easy to get the wrong idea about things when we don't have all the facts. No doubt every market across the country could use more inventory because every market across the country has more buyers than homes to buy, and we want to see more and more inventory come into the market.
I want to give you a perspective from Bill McBride from the Calculated Risk blog, he said this, “Sales, non-seasonally adjusted in September were 548,000. That was 2.7 percent below sales in September of 2020, which was 563,000, but excluding last September, which was obviously distorted by the delayed selling season...were the strongest since 2005!” So, if we take last year's abnormality due to the pandemic out of the equation, then 2021 has had the strongest real estate market on record since 2005! Pretty remarkable. Let me ask you a question here. Do you hear anybody talking about that right now, talking about home sales being very, very good? Maybe a few but certainly not a lot, and you’re certainly not hearing that in the main-stream media!
I firmly believe that headlines do more to terrify than they do to clarify what’s going on, and I'm sure you've seen the clickbait about the real estate market that’s out there that oftentimes misleads people. Maybe the article is factual, maybe the information is factual, but it’s got a clickbait type headline. And many of us don’t bother to read the article because we lead busy lives, and then we just make an assumption off that headline. Perhaps then we discontinue our plans to buy or sell a home and put our life on hold, based on that misleading headline. What a tragedy that could be.
I want to give you a couple of articles that are out there right now, “Foreclosures are shooting up. Is this a repeat of the early 2000s housing crisis?” You know that is a headline that I think we can expect to see more of. I spoke about this recently, about foreclosure starts being up 49 percent last month according to
ATTOM Data, as you can see in the bar graph overlay. And this is an example of being factually correct, but nowhere near where we were in 2019, going back to the more normal market. We should expect foreclosures to be up, as the moratoriums have been lifted. So, expect to see that.
CNBC came out and said this, “Mortgage originations will drop 33 percent in 2022 as interest rates rise according to the industry forecast.” What many of us don’t do, is take the time to read into the article, and I’ll bring that up real quick. If you go into the article, what they actually say is that refinance originations will drop 62 percent in 2022, to 860 billion. Again, that's refinance originations, which is a specific type of mortgage origination, will drop. And that makes sense. In a rising interest rate environment, like we're in right now, we’ll see less refinances. However, they go on to say, “Mortgage originations, for the purpose of buying a home, are forecasted to rise 9 percent, to a record 1.73 trillion next year.” So, the headline doesn’t do really anything to inform a home buyer or even lead them down the right path. You have to go into the article to begin to do that. And over and over, we see and hear these headlines, and start thinking "I don’t know if now is a good time to buy, I don’t know if now is a good time to move forward with my real estate plans." It's unfortunate because we get wrapped up in these headlines and postpone what we want to do because of them. I consider it my duty to bring the truth to the market, so if you want to continue to get the straight scoop please consider subscribing to our channel.
I do want to bring another report in here that I think really emphasizes this point. This is University of Michigan Consumer Sentiment, “Do you think it’s a good time to buy a home?” Well, if you look back at 2020, you know February of 2020, 70 percent of people saying yes, I think it’s a good time to buy a home. Well, if you move forward to September of 2020, a little bit less, 65 percent. Well today, as of September of 2021, about one out of three people think it’s a good time to buy a home. A big reason for that is people have been misinformed about what’s happening in real estate. I've No doubt there are buyers that are frustrated right now. There are buyers who are looking at prices going "it’s getting a little bit too hot". My advice to you is Buy Now, but stay with us and tune in next week when I'll review the housing market 2022 forecast. I'll show you that we’re going to continue to see home price appreciation going into next year.
Friday, October 29, 2021
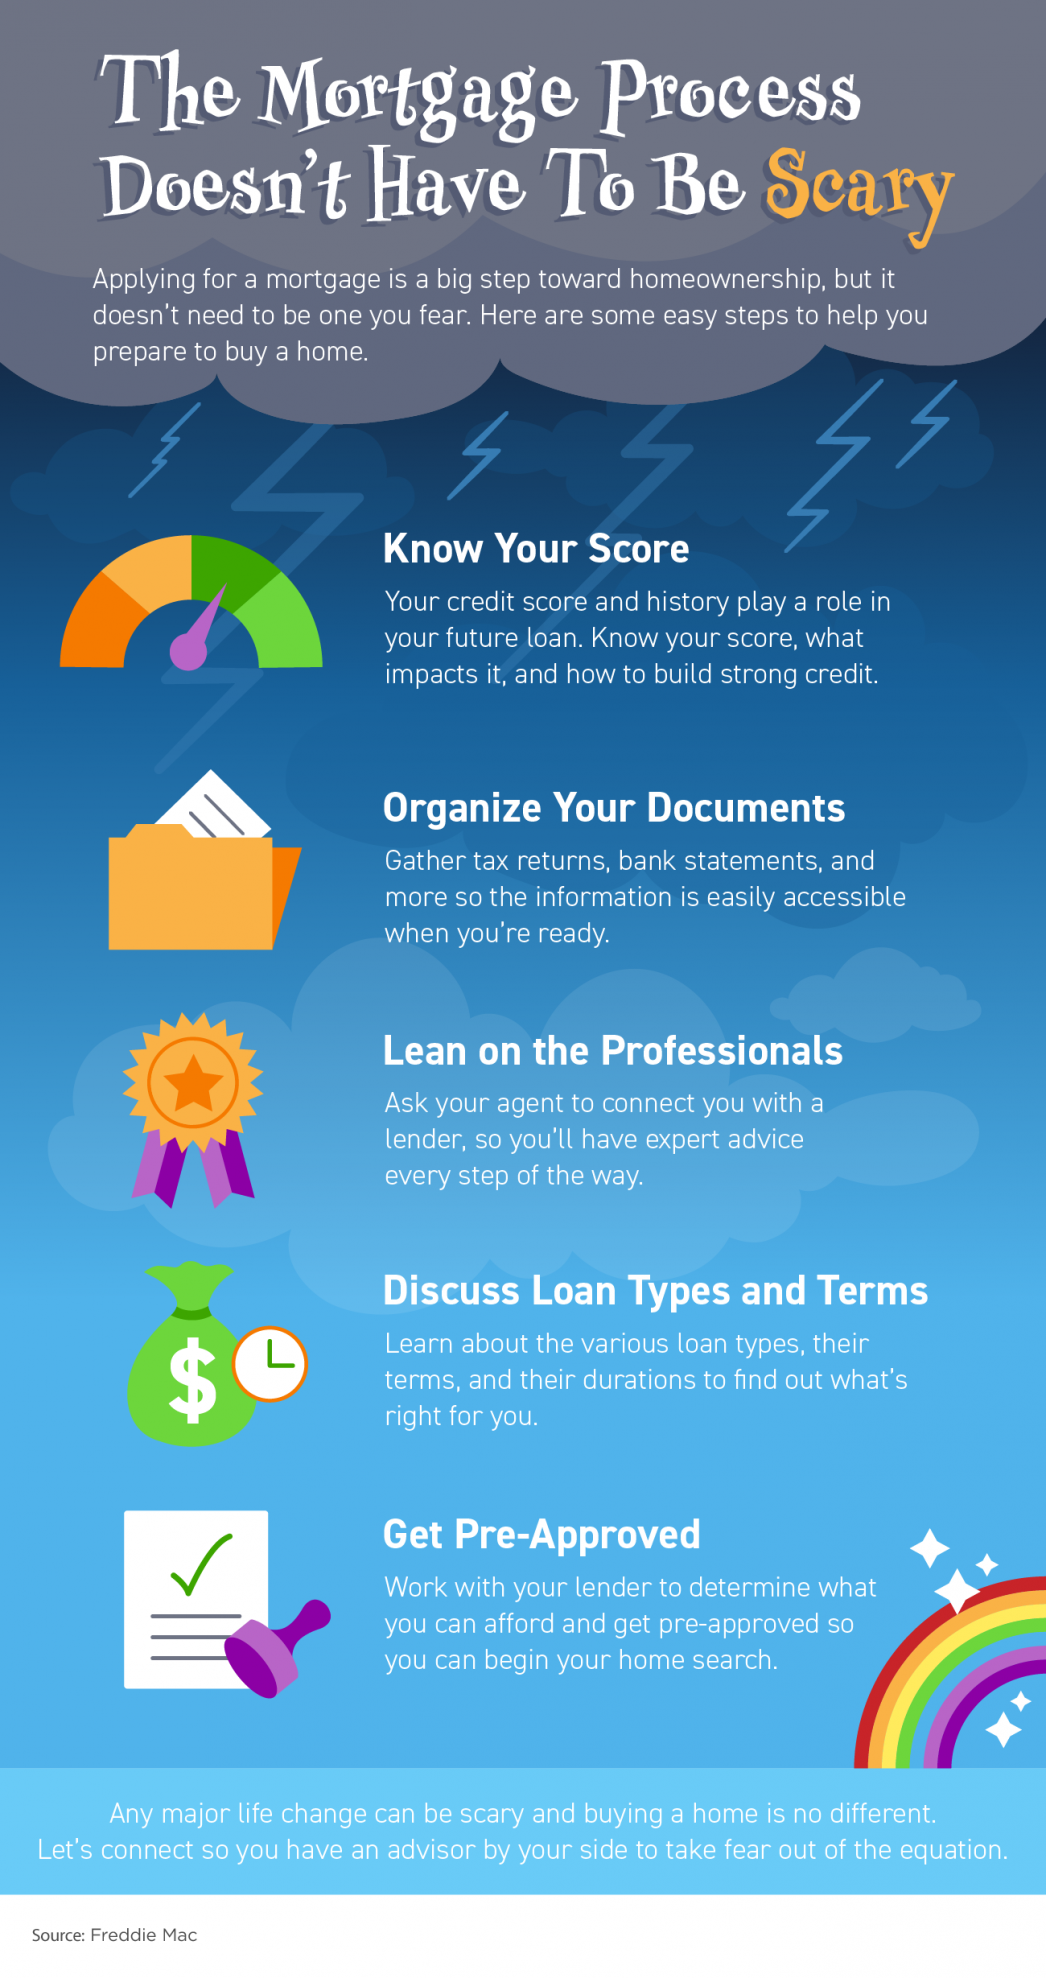
The Mortgage Process Doesn’t Have To Be Scary!
Some Highlights
Applying for a mortgage is a big step towards homeownership, but it doesn’t need to be one you fear. Here are some tips to help you prepare.
Know your credit score and work to build strong credit. When you’re ready, lean on us at Braceland Homes to connect you with a lender so you can get pre-approved and begin your home search.
Any major life change can be scary, and buying a home is no different. Give us a call at Braceland Homes 619-947-3560, so you have an advisor by your side to take the fear out of the equation.
Friday, October 8, 2021
111,285 Reasons You Should Buy a Home This Year
The financial benefits of buying a home versus renting one are always up for debate. However, one element of the equation is often ignored – the ability to build wealth as a homeowner.
According to the latest research from the National Association of Realtors (NAR):
“Homeownership is a key pathway to building wealth and narrowing the racial income and wealth inequality gap. Housing wealth (equity) accumulation takes time and is built up by price appreciation and paying off the mortgage.”
An increase in equity builds the wealth of the individual that owns it. This wealth can be passed down to future generations. The Federal Reserve in an addendum to their Survey of Consumer Finances explains:
“There are numerous ways families can transmit wealth and resources across generations. Families can directly transfer their wealth to the next generation in the form of a bequest. They can also provide the next generation with inter vivos transfers (gifts), for example, providing down payment support to enable a home purchase or a substantial wedding gift.”
The Federal Reserve also explains another way wealth (including the additional net worth generated by an increase in home equity) can benefit future generations:
“In addition to direct transfers or gifts, families can make investments in their children that indirectly increase their wealth. For example, families can invest in their children's educational success by paying for college or private schools, which can in turn increase their children's ability to accumulate wealth.”
Here’s a look at how equity can build your wealth over time when you own a home.
Equity over the Last 30 Years
The NAR research reveals that the average gain for homeowners over the last five years was $139,134 and over the last 10 years was $218,505. Looking even further back in time, the article says:
“Homeowners who purchased a typical single-family existing-home 30 years ago at the median sales price of $103,333 with a 10% down payment loan and who sold the property at the median sales price of $357,700 in 2021 Q2 accumulated housing wealth of $349,258.”
Homeownership builds household wealth which also enables households to more easily move to the home of their dreams. As Mark Fleming, the Chief Economist at First American,explains:
“As homeowners gain equity in their homes, they are more likely to consider using that equity to purchase a larger or more attractive home – the wealth effect of rising equity.”
If you missed out on the equity gains over the last 30 years, don’t fret. Experts are still calling for substantial growth in equity over the next five years.
Looking Forward at the Equity To Come
The most recent Home Price Expectation Survey, a survey of over one hundred economists, real estate experts, and investment and market strategists, expects home values (and therefore equity) to increase as follows:
2021: 11.74%
2022: 5.82%
2023: 3.94%
2024: 3.56%
2025: 3.55%
The survey estimates a 31.8% cumulative appreciation over the next five years. Using their annual projections, the graph below shows the equity build-up a purchaser could earn, using a $350,000 home as an example:That’s a potential increase in household wealth of $111,285 over five years.
Bottom Line
Owning a home is one of the best ways to grow your wealth over time. House wealth can impact generations. In many cases, the largest single investment a household has is their home. As that investment appreciates in value, the financial options also increase. Give us a call at Braceland Homes 619-947-3560 to learn more.
Tuesday, October 5, 2021
4 Tips To Prep for Your Home Sale This Fall
Even in a hot sellers’ market like today’s in which homes are selling so quickly, it’s still important to make a good first impression on potential buyers. Taking the time upfront to prep your house appropriately can bring in the greatest return on your investment.
Here are four simple tips to make sure you maximize the sale of your house this fall.
1. Price It Right
One of the first things buyers will notice is the price of your house. That’s why it’s important to price it right. Your goal in pricing your house is to draw attention from competing buyers and let bidding wars push the final sales price up. Pricing your house too high to begin with could put you at a disadvantage by discouraging buyers from making an offer.
At Braceland Homes, we can help you find the price for your home that reflects the current market value. Lean on your us to help you with this crucial first step.
2. Keep It Clean
It may sound simple, but keeping your house clean is key to making sure it gets the attention it deserves. As realtor.com says in the Home Selling Checklist:
“When selling your home, it’s important to keep everything tidy for buyers. . . . Remember to take special care with the bathroom, making sure the tile, counters, shower, and floors shine.”
Before each buyer visits, assess your space and determine what needs your attention. Wash the dishes, make the beds, and put away any toys. Doing these simple things can reduce any potential distractions for buyers.
3. Make It Easy To Visit
Giving buyers the opportunity to see your house on their schedule can be a true game-changer. Buyers are less likely to make an offer if it’s difficult to plan a tour or they can’t easily fit it into their schedule. Making your house available as often as possible helps create opportunities for more buyers to fall in love with your house.
Rest assured your Braceland Homes will keep your health and safety top of mind when buyers tour your home. Our Agents use the latest guidance to stay up to date on any protocols and sanitization recommendations.
4. Help Buyers Feel at Home
Finally, it’s important for buyers to see all the possible ways they can make your house their next home. As the realtor.com article puts it:
“The goal is to create a blank canvas on which buyers can project their own visions of living there, and loving it.”
An easy first step to create this blank canvas is removing personal items – pictures, awards, and sentimental belongings – from your space. If you’re unsure what should be packed away and what can stay, just ask us. Spending the time on this step can pay off in the long run, as the 2021 Profile of Home Staging from the National Association of Realtors notes:
“Eighteen percent of sellers’ agents said home staging increased the dollar value of a residence between 6% and 10%.”
Bottom Line
To make the most of today’s sellers’ market, avoid the temptation to skip over the essential preparation steps. Call us at Braceland Homes 619-947-3560 today to discuss all the ways you can maximize your home sale.
Saturday, October 2, 2021
Reasons Renters Buy
Some Highlights
When deciding whether you should rent or buy, make sure you’re considering these factors.
Buying a home means consistent monthly payments. Homeownership also helps to build your wealth. And owning a home gives you greater flexibility than renting.
When you’re ready to take advantage of the perks of homeownership, call or text us at Braceland Homes 619-947-3560 so we can explore your options together and set you up for success in your home search.